
Further conflict in the Middle East is likely to cause more uncertainty for manufacturers. Here, we look at what the potential impact will be and what businesses can do to mitigate and risks.
The situation is of course nothing new for manufacturers. In recent years, Russia’s invasion of Ukraine and the disruption to trade passing through the Red Sea, was cause for businesses all over the world to feel uneasy. Not least because of the critical role played by the locations where the upheaval was taking place.
Key takeaways
-
Middle East conflict is increasing supply chain uncertainty: Escalating tensions in the region, particularly around the Strait of Hormuz, are raising concerns about disruption to global energy supplies, shipping routes and trade flows.
-
Energy prices are already rising: Oil prices jumped around 10–13% following the escalation, increasing production costs for manufacturers—especially those in energy-intensive sectors.
-
Shipping and logistics are becoming less reliable: As seen during the Red Sea crisis, some carriers are rerouting vessels around South Africa, adding weeks to transit times and significantly increasing shipping costs.
-
Manufacturers are under growing cost pressure: Higher energy prices, supply interruptions, tighter insurance markets and already elevated UK electricity costs are creating a challenging operating environment for businesses.
-
Resilience and diversification are critical: Manufacturers that diversify suppliers, strengthen partnerships and build flexibility into their supply chains will be better positioned to navigate ongoing geopolitical disruption.
FAQs
- How could conflict in the Middle East affect global manufacturing supply chains?
- Why is the Strait of Hormuz important for global trade?
- How do rising oil prices impact manufacturers?
- Why are shipping routes being diverted during geopolitical crises?
- 5. What can manufacturers do to protect themselves from supply chain disruption?
Ukraine is known as the bread basket of Europe and prior to the conflict the country accounted for 50% of the planet’s sunflower seed oil, 18% of its barley, 16% of maize and 12% of global wheat production. That meant food production and supply suffered.
Likewise, 30% of global container trade passes through the Suez Canal. The 2024 crisis which saw Houthi rebels target trade routes in the Red Sea saw shipping take lengthy diversions around the Cape of Good Hope; adding around 4,000 miles and a 30% increase in transit times to every journey.
The speed and scope of escalation in the Middle East will have taken many businesses by surprise and has highlighted just how unstable the region can become in as little as 48 hours. What will concern companies is that we may just be at the start of a prolonged conflict and there may be much more to come in terms of the impact on global supply chains.
Simon Geale, Executive Vice President, Proxima
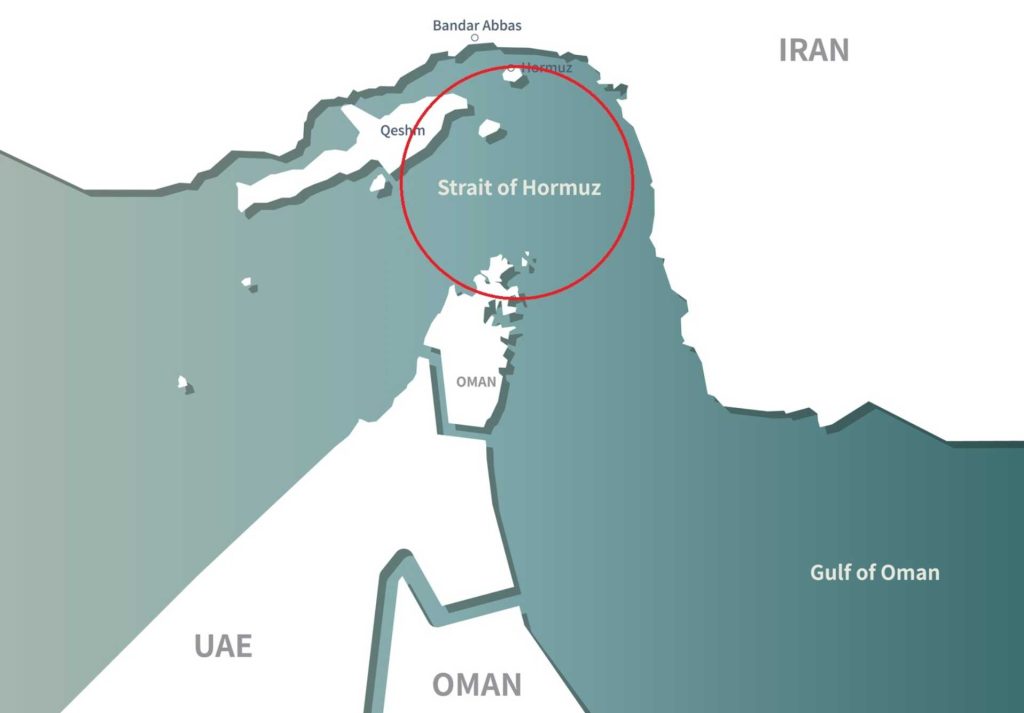
This latest conflict has shone yet another spotlight on the Middle East, with particular reference to the Strait of Hormuz. Located between Iran and Oman, the straight is widely considered the most important energy shipping chokepoint in the world.
A large share of global oil and gas exports from the Persian Gulf must pass through it to reach global markets. Naturally, the last few weeks have left businesses concerned how the conflict will impact both supply and cost.
Simon Geale, Executive Vice President at Proxima, said: “The speed and scope of escalation in the Middle East will have taken many businesses by surprise and has highlighted just how unstable the region can become in as little as 48 hours. What will concern companies is that we may just be at the start of a prolonged conflict and there may be much more to come in terms of the impact on global supply chains.”
Manufacturers are already seeing the impact in terms of supply chain reliability. And in much the same way as the Red Sea crisis, leading carriers are pausing or rerouting services around South Africa. Traffic through the Strait of Hormuz has collapsed from an average of 129 daily ship transits to almost zero, shipping schedules are being extended by weeks, and freight costs are rising sharply.
Brent crude oil rose from around ~$70 to $80–$85 per barrel within days after the conflict escalated, and prices increased about 10–13% during the initial shock to the market. European natural gas prices have also surged 74% in under two weeks, driven by concerns over disrupted LNG flows from the UAE and Qatar, the latter having closed the biggest LNG plant in the world. And for industries like automotive, the disruption to parts and components has already been substantial as vessel traffic through the Strait of Hormuz has plummeted.
Matt Hopkins, Head of Risk Management at Consultus International, commented: “More than 20% of global LNG supply is currently paused, with no clear timeline for continuation. This presents a significant challenge to Europe’s ability to meet demand particularly if the conflict becomes prolonged.
“At this stage, it’s still unclear whether the situation will be short-lived or develop into a longer-term disruption. In the immediate term, organisations should expect continued price spikes at higher levels, reduced availability of prices and contracting, and the widening of bid/offer spreads (the difference between the price to buy and the price to sell).”
All this at a time where industrial electricity prices in the UK are already a staggering four times higher than in the US and 46% above the global average. Almost 90% of UK businesses have seen energy bills rise over the past five years, with four in ten cutting back on investment as a direct result. Still today, business electricity costs remain around 70% higher than before Russia’s invasion of Ukraine.
We are far more proactive in our risk management. This includes diversifying supplier networks, building closer strategic partnerships with material suppliers, increasing visibility across the supply chain, and maintaining more flexible production planning.
Jean Michel Sintome, Director of Operations at Mercian Labels
To make matters worse, the insurance market is also tightening. War‑risk coverage is being withdrawn in parts of the Gulf, and several vessels have already been damaged or stranded. That increases uncertainty for manufacturers and raises the risk of sudden supply gaps.
Other factors that will impact global supply chains include the effective closure of huge swathes of airspace in the Middle East. Airports such as those in Dubai handle both huge numbers of passengers but also cargo, and many closed in the immediate aftermath of conflict breaking out. And while Dubai Airport has resumed limited operations, given the challenges of combating drone strikes, it is possible that further disruption and closures could be on the horizon.
As we see regularly, it’s the manufacturers who are willing to be agile – and who have resilience baked in – that will have the biggest room for manoeuvre. The supply chain disruption of recent years – not only the aforementioned conflicts in the Red Sea and Ukraine, but also Brexit and COVID – has seen more savvy manufacturers diversify their supply chains, explore alternative shipping routes, or tighten contract terms to better allocate risk.
David Roberts, Chairman of automotive manufacturer Evtec Automotive commented: “The conflict in Iran is yet another reminder that the automotive supply chain operates in an increasingly volatile world — and that resilience is no longer optional, it’s a strategic imperative.
“For UK automotive suppliers like Evtec Group, the immediate concerns fall into three broad areas. First, energy costs. Manufacturing is energy-intensive, and any sustained disruption to Middle East oil and gas flows will feed through into price pressure across the sector. At Evtec, we’ve taken steps to mitigate this exposure through longer-term energy and gas contracts, giving us greater certainty on input costs while the market remains unsettled.
“Second, component supply chains. The automotive industry has spent the last five years firefighting supply disruption – from the pandemic to the semiconductor crisis – and the Iran situation adds further complexity to an already stretched picture. Logistics routes through the region matter, and any prolonged instability risks adding lead times and cost to parts moving through those corridors. Suppliers need to be stress-testing their supply chain maps right now, if they haven’t already.
“Third – and perhaps the least discussed – is the downstream demand picture. The MENA region represents a meaningful market for several of our OEM customers, and any significant deterioration in consumer confidence or purchasing power in those markets will eventually work its way back up the supply chain. Reduced OEM volumes mean reduced call-off for suppliers like us.
“The honest truth is that no business can fully insulate itself from geopolitical shocks of this scale. What you can do is build flexibility into your operations. At Evtec, we have a number of established levers we can pull in response to major volume fluctuations, and our focus right now is ensuring those mechanisms are primed and ready.”
Our raw materials don’t come directly from Iran but the instability in the region is slowing some of our shipping routes, creating delays through the supply chain and even impacting the final delivery.
Andy Hill, Sales & Marketing Manager – EMEA, Philadelphia Scientific
Jean Michel Sintome, Director of Operations at Mercian Labels, a UK-based manufacturer specialising in high-quality custom printed labels and packaging solutions added: “The label printing industry relies heavily on global supply chains for materials derived from petrochemicals, including films, resins, coatings and adhesives. Volatility in petrochemical markets can affect the price and availability of key substrates such as polypropylene and polyethylene films, which are widely used across food, beverage, pharmaceutical and consumer goods labelling.
“The UK labels manufacturing sector is still operating in an environment where cost control and supply chain resilience remain key priorities. As a result, we are now far more proactive in our risk management. This includes diversifying supplier networks, building closer strategic partnerships with material suppliers, increasing visibility across the supply chain, and maintaining more flexible production planning.
“In the label printing industry, where turnaround times are often tight and customers operate in critical sectors, maintaining reliability is essential. While it is too early to predict the long-term consequences of the current situation, our focus remains on preparedness and adaptability.”
Andy Hill, Sales & Marketing Manager – EMEA for battery manufacturer Philadelphia Scientific added: “For the past few years now, geopolitical instability is not a new risk that we have to plan for and navigate however, the recent conflict in Iran has added yet another layer of uncertainty at a time when supply chains are only just returning to something that resembles normality.
“Not only do we conduct business with key customers in the region, but the knock-on effects, particularly around energy markets and global logistics, are also impossible to ignore. Manufacturing, especially with volume products, is a margin sensitive environment so when freight and energy costs become unpredictable, everything from production planning on certain product lines to shipping pricing needs a second look and sometimes even a third if it’s delayed even by a few days.
“I think the news concerning the Strait of Hormuz has the potential to drastically shift the fuel prices and freight costs as we have seen a recent $35 swing in the cost of Brent crude which will have an impact on fuel costs, like the ones we’ve already seen at the petrol pumps. Our raw materials don’t come directly from Iran but the instability in the region is slowing some of our shipping routes, creating delays through the supply chain and even impacting the final delivery.
“After the last few years, we’ve learned that it’s not the direct exposure that catches us out, it’s the secondary impacts, like when the Evergreen container got stuck, causing a global chip shortage. In response, we can only take a measured, yet reactive approach, due to the ever-shifting situation that depends on what the US stance is on any given day.
“As more of a safety net, we’re building in slightly larger inventory buffers for critical components and reviewing our logistics partners’ contingency plans. Digital visibility tools are playing a bigger role too, helping us spot early signs of disruption and adjust before issues become costly. We can’t control global events, but we can control how ready we are to deal with anything that is thrown into chaos. Staying calm, staying as informed as we possibly can, and keeping the business resilient no matter how the geopolitical landscape shifts are the only ways we can ride the current storm across two fronts now.”
Dr Richard Smith, Chief Operating Officer and Director at global chemical distribution and ingredients manufacturer 2M Group, added: “Recent developments across the Middle East and surrounding regions underline a reality manufacturers are now very familiar with: global supply chains are increasingly exposed to disruption driven by geopolitical tension, energy markets and logistics constraints. For a business like 2M, operating both as a chemical distributor and manufacturer with global supply networks, the impact is less about direct exposure and more about the knock‑on effects across cost, availability and risk.
“What we see most immediately is volatility. Energy prices, freight capacity, insurance premiums and shipping routes can all change quickly, even where physical supply continues to move. In the chemical sector, fluctuations in oil and gas markets feed directly into raw material costs, while uncertainty around key transport corridors places pressure on lead times, inventory levels and working capital. At the same time, trade controls and compliance requirements continue to evolve, adding further complexity to international manufacturing operations.
“Our response at 2M is focused firmly on resilience rather than reaction. Over recent years we have deliberately diversified sourcing, reduced reliance on single regions, and built flexibility into our supply chains. This includes dual‑source strategies, regional manufacturing and blending capability, and appropriate inventory buffers to protect continuity of supply. We also continue to invest in regulatory and compliance expertise, ensuring we can operate responsibly and without disruption as requirements change.
“We are also seeing customers place greater value on transparency, communication and reliability. In periods of uncertainty, our role extends beyond supplying product to helping customers plan ahead, manage risk and maintain operational stability. That disciplined focus on preparedness and partnership continues to underpin how we support manufacturers globally.”
The honest truth is that no business can fully insulate itself from geopolitical shocks of this scale. What you can do is build flexibility into your operations.
David Robert, Chairman, Evtec Automotive
Stephen Lankfer, Associate Director at Ennovus Solutions, a consultancy helping businesses reduce energy demand and costs added: “Technologies such as solar, small-scale wind, and BESS installed behind the meter can significantly reduce the reliance of these businesses on grid supplied electricity, softening the impact of any market fluctuations.
“A well-engineered system not only increases business resilience, it also reduces operating cost by generating at rates well below current grid rates. This even holds true for fully funded systems with zero upfront costs. Mitigating risk and managing costs is essential to future-proof any business and be prepared for whatever comes next.”
Of course, when it comes to any conflict, the only certainty is uncertainty, and no one knows for sure how long this particular crisis will last and what the long-term impact will be. One thing is for sure, manufacturers can’t go it alone. The sector has been crying out for support form government for quite some time, and this latest hurdle further emphasises that requirement if the UK is to compete internationally.
Not only government, but the British people also have a part to play. Recent years has seen the public come out in loud and vocal support for both the farming and hospitality sectors – both of which were suffering from their own economic frailties. Arguably, the manufacturing industry is even more important for our country, so it’s vital that everyone bangs the manufacturing drum as loudly as possible.
Our response at 2M is focused firmly on resilience rather than reaction. Over recent years we have deliberately diversified sourcing, reduced reliance on single regions, and built flexibility into our supply chains.
Dr Richard Smith, Chief Operating Officer and Director, 2M Group
In an increasingly volatile world, manufacturers cannot afford to rely on stability in global trade. The latest conflict in the Middle East is another reminder that geopolitical events can rapidly reshape supply chains, energy prices and production costs. While the long-term consequences remain uncertain, businesses that prioritise resilience, flexibility and strong supplier relationships will be best placed to adapt. However, resilience cannot rest on industry alone.
If the UK is to remain competitive, manufacturers will need meaningful support from government alongside greater recognition from the public of the sector’s critical role in the economy. In challenging times, collaboration and preparedness will be key to navigating what lies ahead.
For more articles like this, visit our Leadership channel