

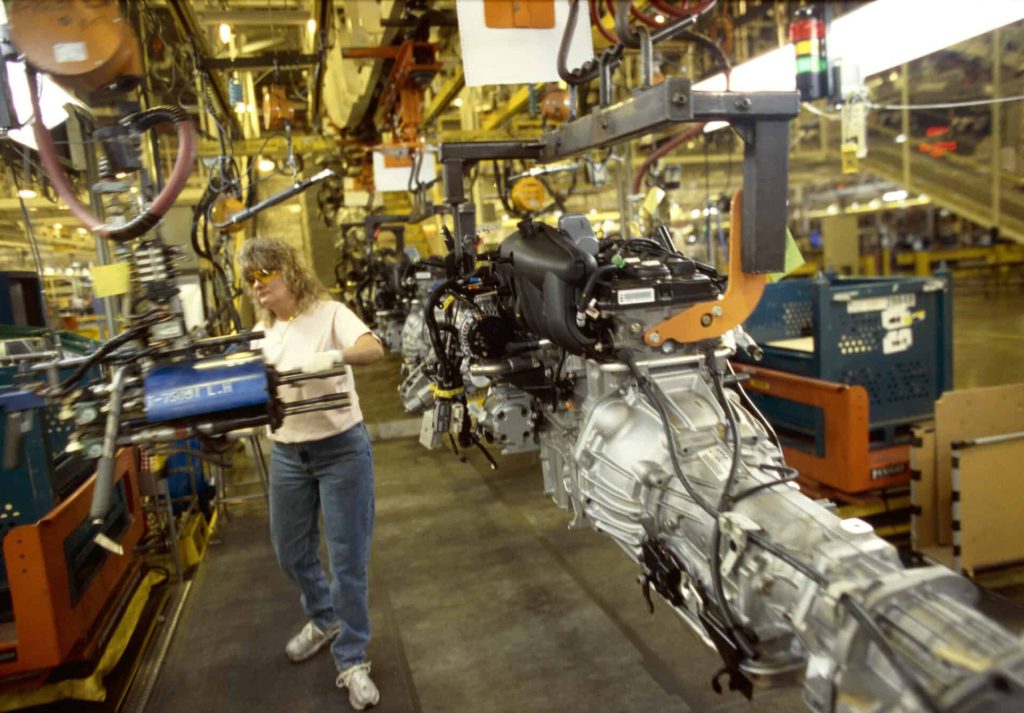
Global supply chains remained underused in October as North American manufacturers scaled back input buying, signaling a slowdown in production, according to the latest GEP Global Supply Chain Volatility Index.
The index, which draws on a monthly survey of 27,000 businesses worldwide, recorded –0.33 in October, indicating that supply chain capacity continues to be underutilized. The data points to a sharp fall in demand for raw materials and intermediate goods in North America, marking the steepest decline since May.
The reduction in input purchasing—often an early signal of factory output trends—suggests that production in the region is likely to weaken in the coming months.
“North America is seeing the clearest sign yet of a manufacturing pullback,” said Michael DuVall, vice president, consulting at GEP. “Manufacturers are buying less and working down inventories, which points to weaker production through the winter. With spare capacity across global supply, we do not anticipate any price pressure, beyond tariffs, on buyers.”
Earlier in the year, North American manufacturers engaged in tariff-driven stockpiling, bolstering inventories ahead of potential trade cost increases. That trend has now reversed, with firms reducing both material purchases and deliberate inventory building, easing pressure on regional supply chains that are now running well below full capacity.
Across Asia, the report showed a broad softening in demand, as a pullback in factory buying in China offset ongoing strength in India. The shift indicates that the region’s industrial momentum is losing steam after months of solid performance.
In Europe, manufacturers reported only a marginal increase in activity, with supplier capacity still underutilized. Firms in Germany, France, Italy, and the U.K. continued to limit raw material purchasing, highlighting the fragility of the continent’s industrial recovery.
Globally, manufacturers are maintaining lean inventories and curbing new orders for inputs, a trend that is helping keep costs stable. With supply chains operating well below full capacity, GEP noted that there is little sign of price pressure emerging, aside from the effects of tariffs.
For more articles like this, visit our Leadership channel