
In this exclusive op-ed for The Manufacturer, the Advanced Propulsion Centre UK’s Shazan Siddiqi argues that while the UK’s automotive sector has strong engineering and R&D capabilities, improving manufacturing competitiveness will require tackling high energy costs, skills shortages and supply chain weaknesses through targeted investment, collaboration and long-term industrial strategies such as DRIVE35.
Manufacturing competitiveness
The UK automotive sector currently stands at the edge of an unprecedented structural shift as it transitions from a century of internal combustion engine dominance toward electrified, autonomous, and software-defined vehicles. This shift represents a race for industrial survival and global relevance. While recent UK vehicle production figures have shown signs of stabilising, according to SMMT, the broader industrial outlook remains challenging as the sector faces intense pressure from a structurally uncompetitive cost base, hollowing supply chains, and aggressive industrial policies from global peers. To secure the next decade of growth, industry leaders and policymakers must move beyond mere declarations of ambition and initiate the hard work of rebuilding domestic manufacturing capability.
The UK’s ability to compete on the global stage is currently hampered by a cost base that makes domestic production difficult to scale. For many manufacturers, the “Britishness” of their product, a brand relied upon by 85% of firms to drive competitiveness, is being undermined by the sheer expense of their OPEX, according to Make UK. Energy costs remain the largest driver of offshoring, with the UK manufacturers facing industrial electricity prices that are over 60% higher than the IEA median and the highest in the G7. This “triple squeeze” of ill-timed contract renewals, policy levies, and grid constraints erode margins and deters the high-capital investment needed for the electric vehicle transition. Proactive government interventions, such as the British Industry Competitiveness Scheme (BICS), are already moving to lower electricity costs, ensuring the UK remains an attractive and bankable location for high-capital industrial investment.
Compounding these energy concerns is a deepening skills crisis that acts as a primary brake on industrial growth. While the UK boasts a world-class engineering pedigree, higher domestic labour costs reduce competitiveness in volume component production. The UK currently has over 52,000 live vacancies in the manufacturing sector as of early 2026, according to Make UK. Furthermore, the UK underinvests compared to international peers, and the nation remains the only G7 member not ranked in the top ten for robotics density, with installation rates less than a tenth of those seen in South Korea. These gaps represent clear, investable opportunities and areas where targeted action can deliver outsized competitive returns.
The UK industrial sector’s primary strengths lie in its R&D and engineering excellence, which serve as the backbone of British industry and anchor high-value technology clusters across the country. Domestic suppliers also benefit from their proximity to major original equipment manufacturers (OEMs), enabling short lead times critical to modern just-in-time manufacturing.
The pathway to onshoring high-value manufacturing must be built on pre-competitive collaboration and a clear-eyed understanding of total logistics costs. Industry leaders, private investors, RTOs, and academia must work together to de-risk technology adoption, with RTOs providing testbeds and demonstrators that enable SMEs to validate processes before making major capital commitments. But collaboration alone is not enough for the tier 2 and tier 3 SME community. They need to be actively listened to regarding the challenges hindering innovation in the community and the constraints they face. These businesses deliver the precision components, sub-assemblies, and specialist process knowledge the whole industry depends on, and keeping them growing and capable within the domestic supply chain is foundational to strengthening UK automotive competitiveness.
Successful onshoring is not just about high-technology components; it requires addressing “commodified” supply chain components that carry hidden overheads. Bulky sub-components like seats and mirrors are often overlooked, yet they are complex systems which incur significant costs when imported from low-cost regions. Major OEMs in the UK are creating future approaches about aggregating the demands of low-cost, high-volume commodity products to increase the viability of their operations in the UK.
The manufacturing productivity roadmap for the next decade necessitates hard-wiring competitiveness into every link of the supply chain through stable, long-term funding programmes. The Advanced Propulsion Centre UK (APC) serves as the critical delivery partner for the Department for Business and Trade’s DRIVE35 programme, a long-term commitment aimed at transforming the UK’s industrial journey. While DRIVE35 continues to support emerging zero-emission technologies, its expanded scope, specifically Theme 2: Enhance Manufacturing Competitiveness, is now one of the solutions in the toolkit for enabling the above-mentioned transformation challenges. If utilised properly, the interventions can provide a strong opportunity and a solid foundation for the UK’s automotive manufacturing.
To learn more about DRIVE35 funding, visit www.apcuk.co.uk/funding or email [email protected]
About the author
Shazan Siddiqi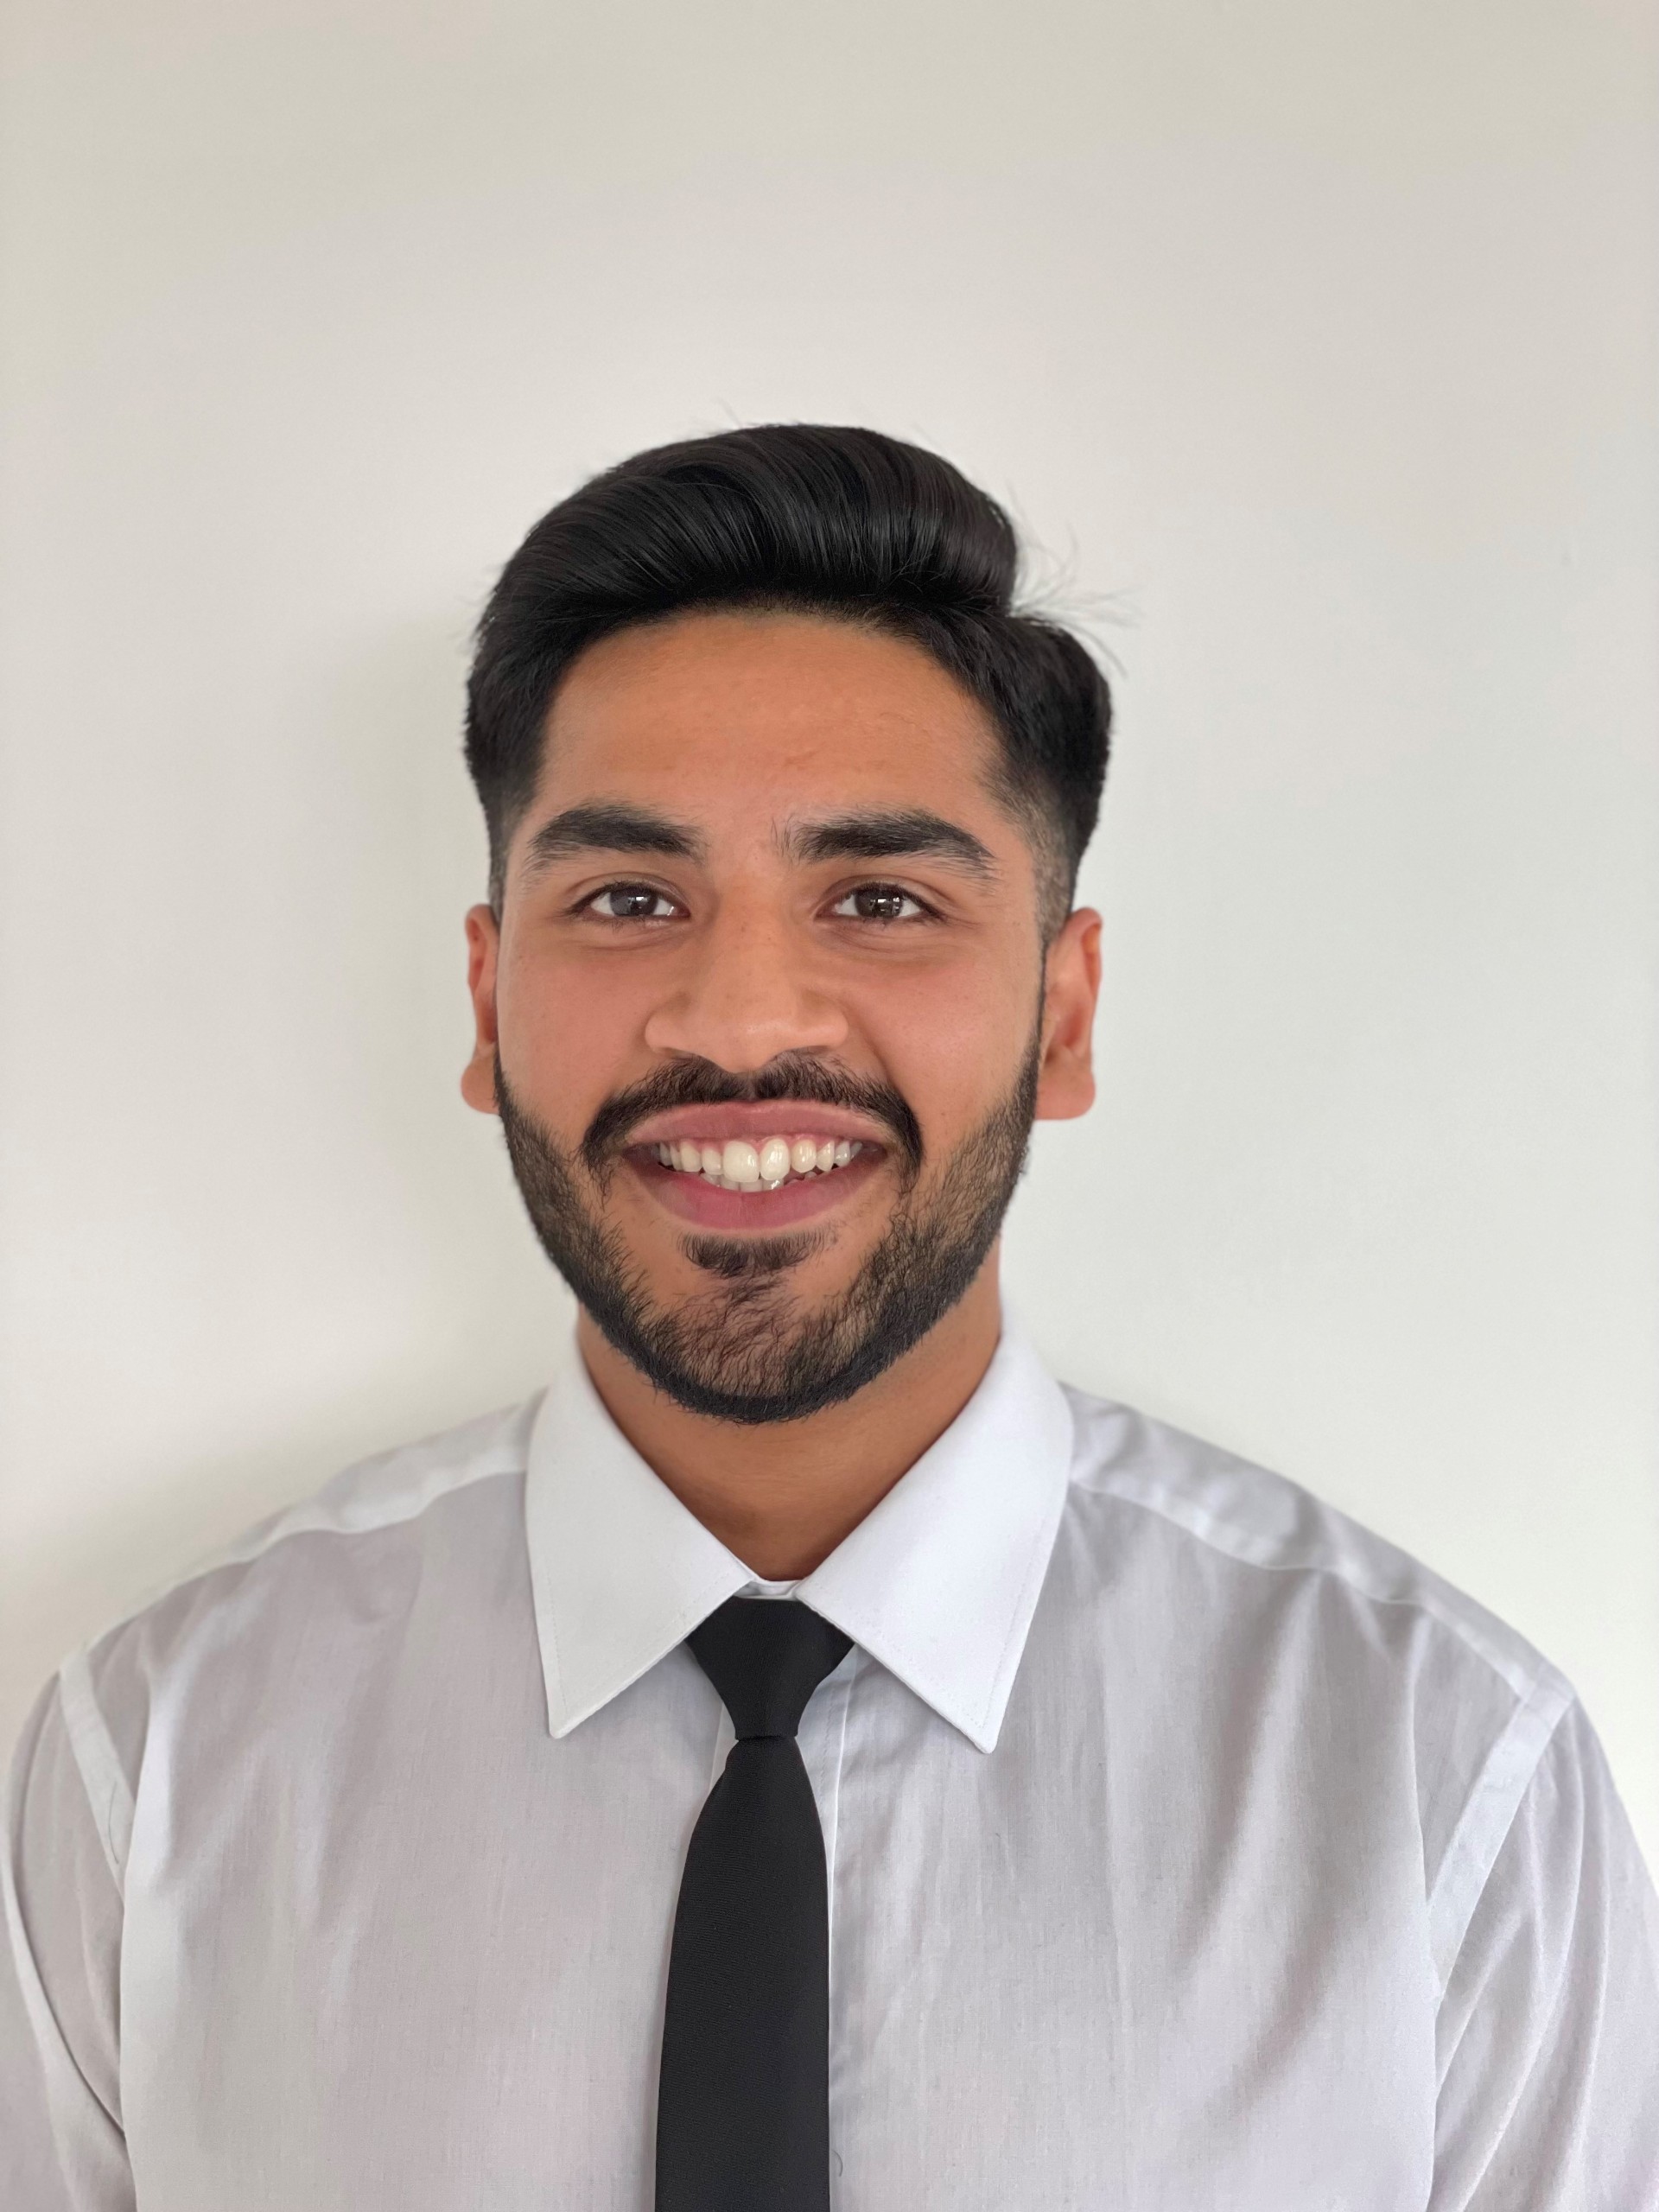 , Automotive Trends Strategist, the Advanced Propulsion Centre UK (APC UK).
Shazan is an Automotive Strategist at the Advanced Propulsion Centre UK, where he conducts strategic research on global automotive trends, advanced manufacturing, and supply chain transformation to support the UK’s transition to a net-zero mobility ecosystem. His work focuses on analysing emerging technologies, market dynamics, and policy frameworks to inform industrial strategy, investment prioritisation, and future mobility planning.
With a background in automotive strategy, electric mobility, and energy storage markets, Shazan has led extensive research into EV infrastructure, commercial vehicle electrification, emerging battery technologies, and evolving mobility business models. He specialises in translating complex technical and market intelligence into clear, actionable insights for industry leaders and policymakers.
For more articles like this, visit our Leadership channel