

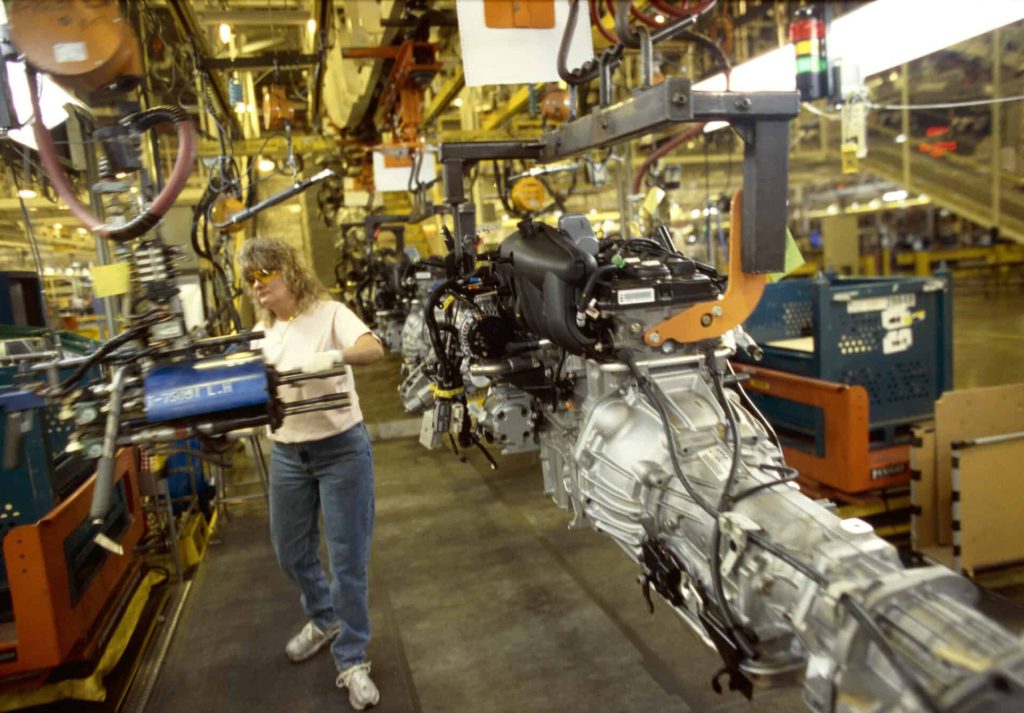
U.S. factory output rose in January at its fastest pace in almost a year, offering a modest sign of resilience in the industrial sector even as overall capacity utilisation remains below long-term averages.
According to the Federal Reserve, industrial production increased 0.7% in January, following a 0.2% gain in December. Manufacturing output—the largest component of industrial activity—advanced 0.6%, marking its biggest monthly rise since February 2025.
Capacity utilisation climbed to 76.2%, though it remained 3.2 percentage points below its long-run average, suggesting continued slack across U.S. industrial operations.
The January increase was widely distributed across sectors. Durable goods production rose 0.8%, supported by stronger output in machinery, computer and electronic products, motor vehicles and parts, and nonmetallic mineral products. Nondurable manufacturing output increased 0.4%, with gains in chemicals, plastics and rubber products, and paper-related industries offsetting declines elsewhere.
Among major market groups, production of consumer goods rose 0.7%, business equipment climbed 0.9%, and materials output increased 0.6%. Output of nonindustrial supplies also advanced 0.9%.
Despite January’s improvement, factory operating rates remain below historical norms. Manufacturing capacity utilisation rose to 75.6%, still 2.6 percentage points below its long-run average. Mining utilisation edged down to 84.4%, and utilities utilisation reached 72.9%, both also trailing long-term benchmarks.
The figures indicate that while production is picking up, manufacturers still have room to increase output without significant new investment in capacity.
January’s data suggest continued stabilisation in U.S. manufacturing after a period of slower growth tied to higher interest rates, inventory adjustments and softer global demand. Economists will watch upcoming reports to determine whether the improvement signals sustained momentum or a short-term rebound.
For manufacturers, the combination of rising output and underused capacity points to cautious optimism, but the sector has yet to fully recover to its historical operating levels.
Interested in hearing about the latest North American manufacturing news right in your inbox each week?
Sign up to The Manufacturer Digital Briefing – North American Edition