

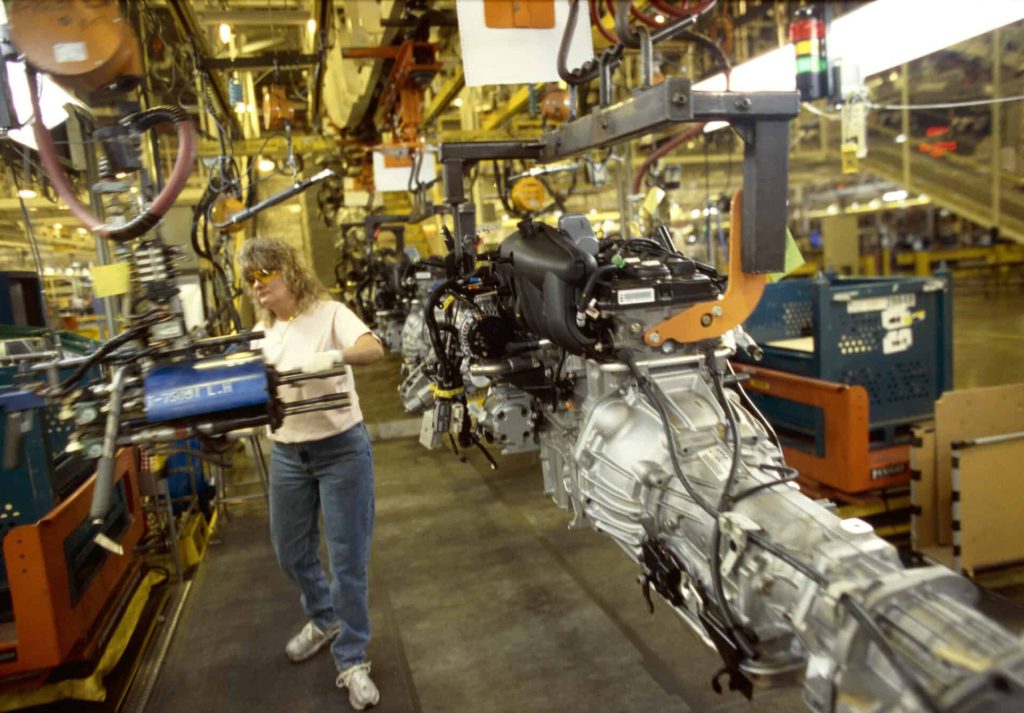
US manufacturing activity continued to expand in December, albeit at a slower pace, as a renewed decline in new orders offset solid output growth and strengthening employment, according to the latest S&P Global US Manufacturing PMI data.
The seasonally adjusted headline PMI eased to 51.8 in December, down from 52.2 in November, marking the weakest reading in the current five-month expansion. While the index remained above the 50.0 threshold that signals growth, the data pointed to a loss of momentum as demand conditions softened toward the end of the year.
New orders fall for first time in a year
The slowdown was driven primarily by a contraction in new order intakes, the first decline recorded in exactly a year. Although the fall was described as mild, it marked a notable shift after a prolonged period of steady demand growth.
Export orders continued to act as a drag on overall sales, declining for the seventh consecutive month. Survey respondents again linked weak international demand to the impact of tariffs, with export sales to Canada cited as particularly affected.
As a result of softer demand, manufacturing output growth moderated in December, posting its slowest expansion in three months. Despite this easing, production levels remained sufficiently strong for firms to continue building inventories of finished goods for a fifth successive month, though the pace of stock accumulation slowed sharply from November’s survey-record high.
Hiring strengthens as firms look to 2026
In contrast to weakening order flows, employment growth accelerated. Manufacturers reported a solid rise in staffing levels, with job creation the strongest since August, as firms expanded labour capacity and filled vacancies in anticipation of improved conditions in 2026.
This increase in workforce capacity contributed to a further reduction in backlogs of work, which fell for the fourth month running. The decline in work outstanding reflected both weaker incoming orders and firms’ efforts to work through existing workloads.
Business confidence remained positive overall, with manufacturers continuing to expect higher sales and production over the year ahead. Optimism was linked to hopes of lower interest rates, alongside planned business expansion and investment. However, sentiment eased slightly compared with November amid ongoing uncertainty around tariffs and the lack of new orders to replace completed work.
Tariffs keep price pressures elevated
Cost pressures remained a prominent feature of the December survey. Tariffs were again reported to be pushing up input prices, as suppliers raised charges. While input cost inflation slowed to an 11-month low, it remained historically elevated.
Output prices followed a similar trend. Manufacturers recorded the slowest rise in selling prices since the start of 2025, but charge inflation stayed comfortably above its long-run average.
Higher prices and subdued demand discouraged purchasing activity, with overall input buying stalling during the month. Where firms did increase purchases, this was largely attributed to efforts to build inventories as protection against further price rises, contributing to a fifth consecutive rise in pre-production stocks.
Supplier performance also deteriorated, with capacity constraints leading to longer delivery times. Average lead times lengthened at the fastest rate in seven months, adding another layer of pressure to manufacturing supply chains as the year drew to a close.
Chris Williamson, Chief Business Economist at S&P Global Market Intelligence, said: “Although manufacturers continued to ramp up production in December, suggesting the goods producing sector will have contributed to further robust economic growth in the fourth quarter, prospects for the start of 2026 are looking less rosy.
“Something of a Wiley E Coyote scenario has developed, whereby – just like the cartoon character continues to run despite chasing the roadrunner off a cliff– factories are continuing to produce goods despite suffering a drop in orders. The gap between growth of production and the drop in orders is in fact the widest seen since the height of the global financial crisis back in 2008-9. Unless demand improves, current factory production levels are clearly unsustainable. Payroll numbers will also be adversely impacted if production capacity has to be scaled back.
“A key factor causing concern over sales is the extent to which producers are having to pass higher costs on to customers in the form of raised prices, with higher costs continuing to be overwhelmingly blamed on tariffs.
“Some encouragement comes from input cost inflation moderating in December to the lowest recorded since last January. However, while this cost trend suggests the tariff impact on inflation peaked back in the summer, costs are still rising month-on-month at an elevated rate to suggest that US firms continue to face higher cost growth than competitors in most other major economies.”
Interested in hearing about the latest North American manufacturing news right in your inbox each week?
Sign up to The Manufacturer Digital Briefing – North American Edition