
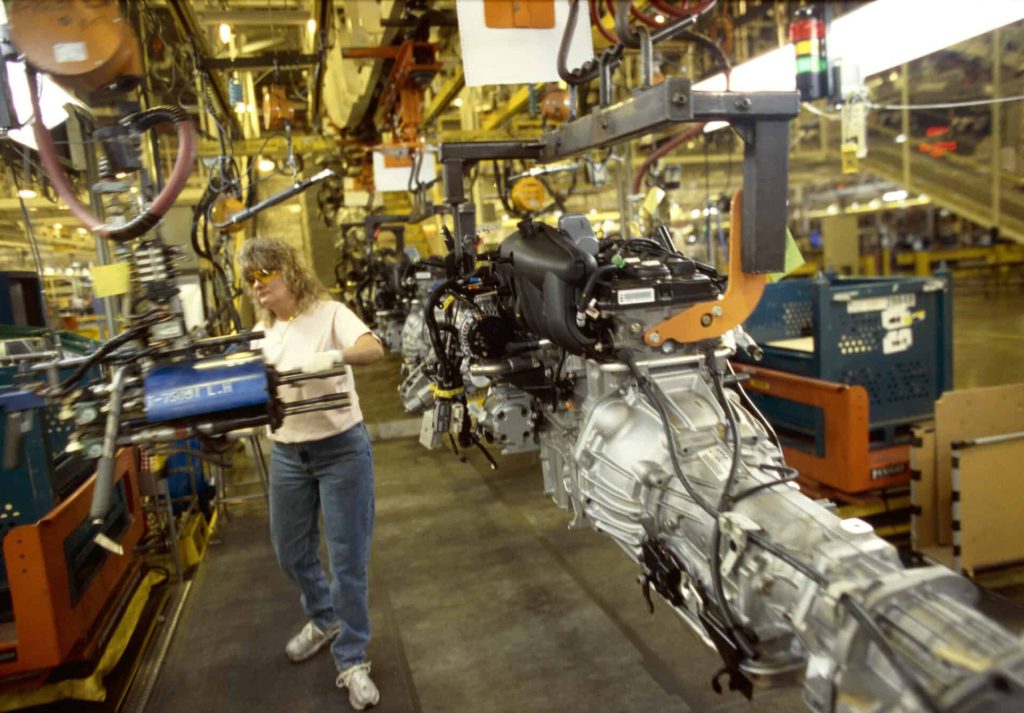
US manufacturing remained in expansion territory in July, but slowing production, weaker demand and mounting supply chain disruption suggest the sector is entering the second half of the year with growing caution.
The latest S&P Global US Manufacturing PMI held steady at 53.9 in July, unchanged from June and marking a full year of improving operating conditions. However, the headline figure masked a slowdown in output and new orders, alongside falling business confidence and worsening supplier delays.
Production expanded at its weakest pace since March, while new order growth eased for the third consecutive month. Manufacturers reported that new customer wins were increasingly offset by raw material shortages, subdued customer confidence and inflationary pressures.
International demand remained a weak spot, with export orders declining again as tariffs and softer overseas demand continued to weigh on sales. Growth was instead driven primarily by the domestic market.
Supply chain pressures also intensified during the month. Vendor performance deteriorated at one of the fastest rates seen in the past four years, contributing to slower growth in purchasing activity and inventories of production inputs. Many manufacturers reported sourcing difficulties and delivery delays linked to ongoing conflict in the Middle East, while inventories of finished goods fell for the first time in four months as companies fulfilled orders from existing stock.
Cost pressures remained elevated despite moderating slightly. Survey respondents continued to cite higher energy prices and tariffs as key drivers of input cost inflation, with many firms passing at least part of those increases on to customers through higher selling prices.
Hiring activity also remained subdued. Employment increased only marginally in July, with many firms indicating that recent recruitment needs had largely been met. At the same time, backlogs of work continued to rise modestly, suggesting capacity is becoming increasingly constrained by material shortages rather than labour availability.
Chris Williamson, Chief Business Economist at S&P Global Market Intelligence, said the steady headline PMI masked signs of weakening momentum.
“Although the headline PMI held steady in July, beneath the survey we see some warning signs about the future growth trajectory.”
He said production growth had slowed significantly following strong inventory building during the second quarter, while manufacturers were facing additional pressure from supply chain delays, weaker exports and customer resistance to higher prices.
“While input cost inflation moderated slightly, inflationary pressures remained elevated thanks principally to the combination of high energy prices and tariffs,” Williamson added.
“In this environment, business optimism about growth prospects slipped to the lowest since last October, underscoring the downside risks to the near-term outlook.”
Despite those concerns, manufacturers remained broadly optimistic that production will continue to grow in the months ahead. However, confidence fell for the third consecutive month to its lowest level since October 2025 as businesses became increasingly concerned about inflation, slowing sales growth and persistent disruption across global supply chains.
Never miss a North American manufacturing story
Sign up for our free weekly North American Manufacturing Digital Briefing to receive the latest industry news, insights and analysis direct to your inbox every Monday.