Cambridge Industrial Innovation Policy has published the UK Innovation Report 2026. The report’s co-authors speak to The Manufacturer about the findings and what they mean for the sector.
The UK has long been recognised as one of the world’s leading innovation economies. It ranks among the top countries globally for scientific publications, high-impact research and patents in critical technologies, and has developed one of the most dynamic start-up ecosystems outside the US.
Key takeaways
- Strong research performance, weak industrial conversion: The UK is a global leader in research, publications, patents, and start-up creation, but this strength is not translating into sustained industrial competitiveness, export growth, or productivity gains.
- A major ‘scale-up gap’ is limiting value capture: While the UK produces many successful start-ups and spinouts, too many are acquired abroad or scale overseas. As a result, much of the economic value from UK innovation is not retained domestically in production or exports.
- Innovation success is concentrated in a few sectors: Growth and scale-up activity is heavily focused in areas like fintech, software, and life sciences, while manufacturing-heavy and strategic sectors struggle to turn innovation into long-term industrial strength.
- Manufacturing shows productivity gains but declining scale: Sectors like electronics are becoming more productive but are losing employment and global competitiveness, with the UK running trade deficits and shifting toward niche, high-value specialisms rather than mass production.
- Skills shortages are a structural barrier to growth: Engineering and science roles face persistent recruitment challenges, with most new jobs requiring higher-level qualifications. These shortages are long-term and could significantly limit the UK’s ability to implement its industrial strategy effectively.
FAQs
- What is the main finding of the UK Innovation Report 2026?
- Why is the UK considered to have a ‘scale-up gap’?
- Which sectors are driving UK innovation growth?
- What challenges does UK manufacturing face despite strong productivity?
- How do skills shortages impact UK industrial strategy?
Yet, as the government moves from designing its Industrial Strategy to delivering it across eight priority sectors, a more fundamental question is coming into focus for industry: can the UK convert its research strength into sustained industrial competitiveness?
The newly published UK Innovation Report, from the Cambridge Industrial Innovation Policy, based at the Institute for Manufacturing, University of Cambridge, argues that this translation challenge now sits at the heart of the UK’s economic future.
The report provides a comprehensive evidence base on the UK’s innovation performance, drawing on new data and sector-level analysis across the Industrial Strategy’s priority areas. It sets out not only the scale of the UK’s research strengths but also the structural barriers limiting their translation into industrial outcomes.
The findings were presented to industry, policymakers and researchers at the report’s official launch event at the Institute for Government, highlighting the growing urgency of aligning innovation policy with industrial competitiveness.
Strong research, weaker industrial outcomes
The UK’s research performance remains internationally strong. In 2023, the UK ranked sixth globally for total R&D expenditure, accounting for 3.5% of global spending. R&D intensity stood at 2.68% of GDP, below the OECD average and leading R&D-intensive economies, though above several G7 peers and China.
In 2022, the UK ranked fourth worldwide for total publications and was among the top five for highly cited outputs in technology fields across the physical sciences and life sciences. It was also among the global leaders in patent applications in areas such as artificial intelligence, biotechnology and semiconductors.
Yet this strength has not proportionately translated into industrial advantage at a time of intensifying global competition. The report finds, for example, that the UK has a relatively low share of high-technology exports in total trade, and its representation among the world’s top R&D-investing firms has declined since 2012.
Considering the Industrial Strategy’s stated objectives, the question is how the UK’s research strength connects to domestic production, export performance and sustained industrial capability
Carlos López-Gómez, Co-author, UK Innovation Report 2026
The UK ranks among global leaders in start-up creation and has produced a high number of so-called ‘unicorn’ firms. However, this success has not translated into sustained productivity growth, export dynamism, or deeper domestic industrial capacity.
That challenge is central to the UK’s industrial future, according to Carlos López- Gómez, Co-author of the report. “The UK performs strongly on research excellence and scientific output, but research excellence alone does not guarantee industrial competitiveness. Considering the Industrial Strategy’s stated objectives, the question is how this research strength connects to domestic production, export performance and sustained industrial capability. The UK cannot simply become the ‘lab of the world’, with new products and services based on knowledge created here but produced abroad.”
The scale-up gap: where value leaves the UK
UK technology scale-up activity is concentrated in a narrow set of sectors, notably life sciences, software and fintech. While the UK performs strongly in early-stage innovation, since 2012 most university spinout IPOs have taken place overseas, and acquisitions of UK firms by foreign companies have increased significantly over the past decade.
For industry, these patterns point to a persistent challenge in domestic value capture. While the debate focuses almost exclusively on access to finance, structural factors – including access to supply chains, specialised skills, regulatory conditions, and market scale – influence where long-term industrial benefits are realised.
The report highlights that technology scale-up should not be defined by firm valuation or capital raised alone – but by the extent to which companies build domestic production capacity, exports and sectoral depth over time. The concentration of scale-up activity in a limited number of sectors helps to explain why strong innovation performance has translated unevenly into competitiveness across manufacturing-intensive and other strategic sectors.
Carlos added: “Industrial strategy must focus less on the number or valuation of high-growth firms and more on whether innovation helps to regain competitiveness in priority sectors.”
Electronics and electrical equipment: productivity without scale, a warning sign?
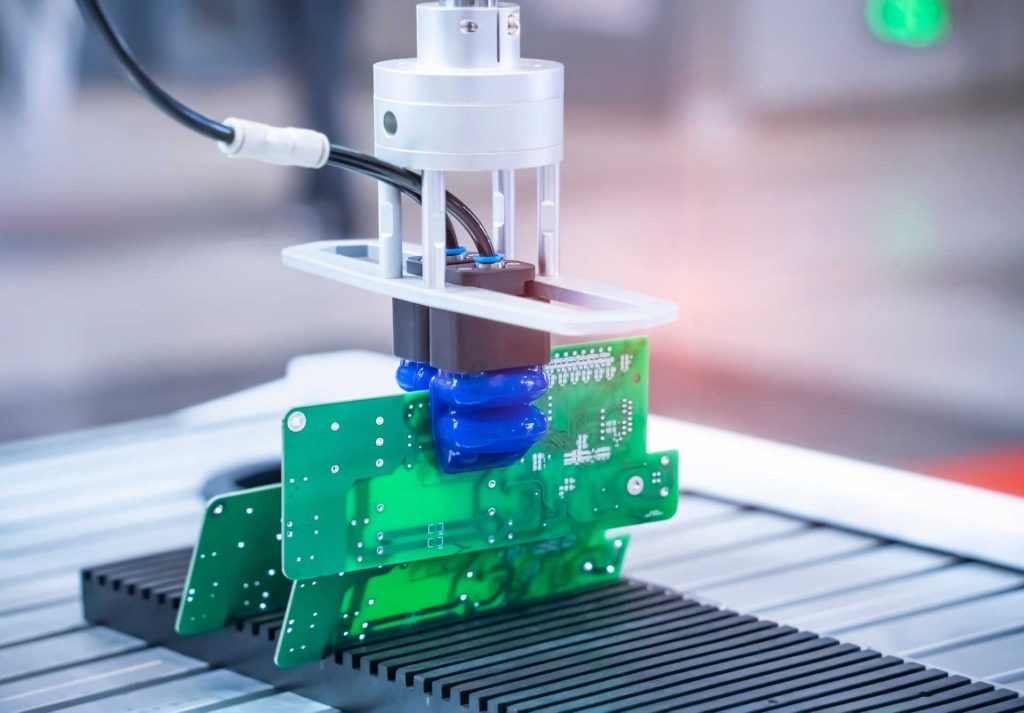
The report’s analysis of the electronics and electrical equipment sectors illustrates the broader structural shift in UK manufacturing. Together, these sectors account for 10% of UK manufacturing value added and 13% of manufacturing exports.
Electronics has grown faster in value added than manufacturing overall since 2000, and performs strongly in labour productivity. At the same time, both electronics and electrical equipment have seen long-term employment reductions, and the UK runs trade deficits in both sectors.
The central challenge is not whether the UK produces worldclass science but whether it can convert that strength into a durable industrial advantage.
Carlos López-Gómez, Co-author, UK Innovation Report 2026
The findings highlight a transition away from scale and volume towards highly productive, knowledge-intensive niches embedded in global value chains. Competitiveness increasingly rests on strengths such as metrology, photonics, medical technologies and specialised grid-related equipment rather than high-volume, low-cost products.
“The real opportunity for the UK lies in reversing the long-term decline of high-value-added sectors,” said report Coauthor, Zongshuai Fan. “The UK has an enviable research and innovation base, but the challenge is ensuring that these capabilities support the competitiveness and growth of its industrial sectors.”
Skills and workforce constraints
The report identifies workforce pressures as a structural constraint on competitiveness. A total of 64% of the workforce in the eight priority sectors identified in the Industrial Strategy hold graduate-level qualifications, compared with 52% across the economy. Around 82% of new jobs in priority occupations between 2025 and 2030 are expected to require post-secondary education.
Despite overall vacancy levels easing, skills shortages persist. In 2024, skills shortage vacancies accounted for 27% of all vacancies. In 2025, 76% of engineering employers reported difficulties recruiting workers with the required skills, with specialist sustainability skills most frequently cited as the main challenge.
Co-author Michele Palladino added: “The data suggests that current shortages are structural rather than cyclical, particularly for science and engineering professionals. Without closer alignment between skills and industry needs, workforce constraints could limit the effectiveness of industrial strategy implementation.”
A pivotal moment for UK manufacturing
The publication of the UK Innovation Report 2026 comes at a critical juncture. As the UK transitions from strategy design to implementation, the challenge is no longer defining ambition but delivering results.
For the manufacturing sector, the implications are clear. Innovation alone is not enough. The key question is whether the UK can convert its world-class science base into competitive, productive and export-oriented industrial activity.
“The evidence highlights three areas requiring particular focus: strengthening the link between research excellence and domestic industrial scale; supporting later-stage technology deployment and adoption within priority sectors; and addressing structural skills and capability constraints that limit growth,” Carlos said.
Ultimately, the report makes a compelling case that competitiveness and the creation of high-quality jobs should be the benchmark for success.
“The central challenge is not whether the UK produces world-class science but whether it can convert that strength into a durable industrial advantage in an increasingly competitive global environment. Together, the findings in the Innovation Report suggest that competitiveness and good jobs – not innovation activity alone – should be the benchmark for success.”
For more articles like this, visit our Innovation channel